


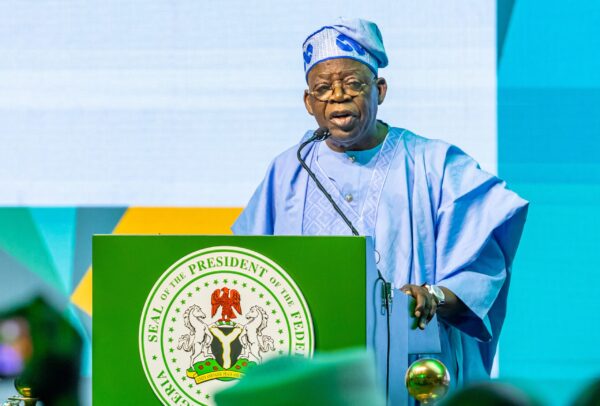
President Bola Tinubu has said his administration is changing Nigeria’s long-standing record of economic underperformance, citing increased gross domestic product (GDP) growth, rising capital inflows and improvements in manufacturing.
Tinubu, represented by Vice President Kashim Shettima, spoke on Monday while declaring open the 32nd Nigerian Economic Summit in Abuja. The event was themed “Growth That Works: Delivering Jobs, Productivity and Shared Prosperity”.
According to a statement by Stanley Nkwocha, Senior Special Assistant to the Vice President on Media and Communications, the President said the government’s reforms were intended to stabilise the economy, attract investment and create jobs.
“We came to rewrite the story of a nation that has performed below its potential for far too long. But there is no shortcut to economic growth,” Tinubu said.
Zebra News reports that the President cited National Bureau of Statistics figures showing that Nigeria’s inflation-adjusted GDP grew by 3.89 per cent in the first quarter of 2026, compared with 3.13 per cent in the corresponding period of 2025.
He said non-oil activities accounted for 96.08 per cent of GDP, while manufacturing and the oil sector grew by 3.29 per cent and 2.57 per cent respectively.
Tinubu also disclosed that capital importation reached $10.37bn in the first quarter of 2026, representing an 83.83 per cent increase compared with the same period in 2025.
He pledged to continue reducing regulatory barriers, improving transparency and expanding access to finance. However, he acknowledged that more work was needed, particularly in electricity market reforms, agricultural value chains and domestic processing of solid minerals.
United Nations Deputy Secretary-General Amina Mohammed acknowledged the gains from the reforms but called for their consolidation and stabilisation, alongside careful management of public expectations.
Finance Minister Taiwo Oyedele presented a draft Nigerian Economic Policy Framework and invited the Nigerian Economic Summit Group and private-sector experts to review the proposal.
NESG Chairman Olaniyi Yusuf urged the government to stabilise the reforms rather than reverse them, while BUA Group Chairman Abdul Samad Rabiu welcomed improvements in access to foreign exchange for businesses.
Tinubu removed the petrol subsidy and unified the naira’s exchange rates shortly after assuming office in May 2023. While the policies were associated with efforts to attract investment and improve foreign exchange access, they were also followed by higher inflation and a severe cost-of-living crisis.
The Nigerian Economic Summit, established in 1993, serves as a platform for dialogue between the government and private sector on the country’s economic policies and development priorities.
