


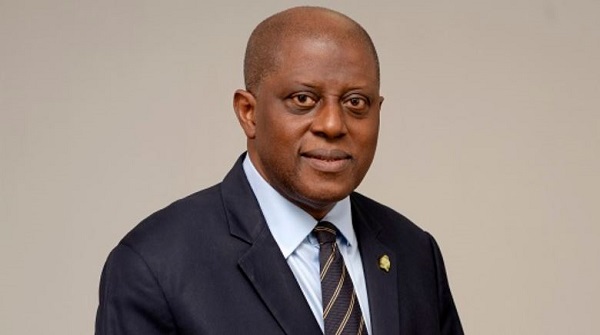
Central Bank of Nigeria (CBN) Governor Olayemi Cardoso says the country’s foreign reserves have risen to $46.7 billion, the highest level in almost seven years.
Cardoso disclosed the figures on Thursday while briefing the Senate Committee on Banking, Insurance and Other Financial Institutions. He said the reserves now provide 10.3 months of import cover, reflecting renewed confidence in Nigeria’s economic direction.
According to the CBN governor, recent gains stem from improved stability in the foreign exchange (FX) market, strengthened monetary policy, and growing investor confidence.
Exchange Rate Gap Narrows Sharply
Cardoso told lawmakers that the spread between the official market and the parallel market has narrowed to below 2 percent, down from more than 60 percent a year ago.
He added that the average exchange rate in the Nigerian FX market has appreciated to ₦1,442.92 per dollar as of November 26, compared with ₦1,551.08 recorded in the first half of 2025.
Diaspora remittances have also surged by 66.7 percent, rising from about $200 million monthly to approximately $600 million in recent months.
“Another important outcome was the resolution of the $7 billion verified FX backlog, restoring credibility and confidence in the Nigerian economy,” Cardoso said.
Inflation Falls for Seventh Straight Month
The CBN governor noted that headline inflation has fallen for seven consecutive months to 16.05 percent in October — the lowest in three years. Food inflation, he said, dropped to 13.12 percent.
He added that real GDP grew by 3.98 percent in the third quarter of 2025, driven largely by crop production, ICT, real estate and financial services.
Cardoso described the economic outlook for 2026 as “very positive,” noting that Nigeria now ranks among Africa’s most advanced digital payments markets, powered by a vibrant fintech ecosystem that has produced eight of the continent’s nine unicorns.
Senate Committee Commends CBN
Senator Tokunbo Abiru, chairman of the committee, commended the CBN for what he described as “remarkable macroeconomic improvements” observed since the lawmakers’ last engagement with the bank in July.
“These positive indicators have not gone unnoticed globally,” Abiru said.
“I commend the bank and its leadership for the role played in earning the country favourable ratings from Fitch and S&P Global Ratings, reflecting improved investor sentiment, policy credibility, and macroeconomic stability.”
